
Index Funds, Explained Without the Jargon
Investing has a reputation problem. It sounds like something done by people in suits who read earnings reports for fun. In reality, the most reliable wealth-building strategy available to a young professional is almost aggressively boring: buy a broad slice of the entire market, keep costs low, and leave it alone for decades. That is the core idea behind index funds, and understanding it takes about ten minutes.
What an index fund actually is
An index is just a list — a rule for deciding which companies or bonds to include. A broad stock index might include thousands of companies across many industries and countries. An index fund is a fund that simply holds everything on that list, in proportion, instead of paying a manager to pick favorites. Because there is no team of analysts making judgment calls, index funds tend to charge very low fees. That matters more than most people realize, because fees compound against you the same way returns compound for you.
When you buy an index fund, you are not betting on one company. You are betting on the overall productive capacity of the market — thousands of businesses hiring, selling, and innovating. Some will fail. Some will soar. Historically, the broad market has trended upward over long periods, though it absolutely does not do so in a straight line. Drops of 20% or more happen, and they are normal. The investors who do well are usually the ones who keep buying through the drops instead of panicking.
A simple structure that works for most people
You do not need a complicated portfolio. A common approach is a small number of low-cost funds: one covering broad domestic stocks, one covering international stocks, and one holding bonds. The bond portion acts as a stabilizer, and how much you hold usually depends on your time horizon. If you will not touch the money for thirty years, you can hold very little in bonds. If you might need it in five, you probably want more.
Where you hold investments matters too. Tax-advantaged accounts like a 401(k) or IRA should generally be filled before a regular brokerage account, because the tax savings are free money. Within those accounts, the funds themselves are usually the same.
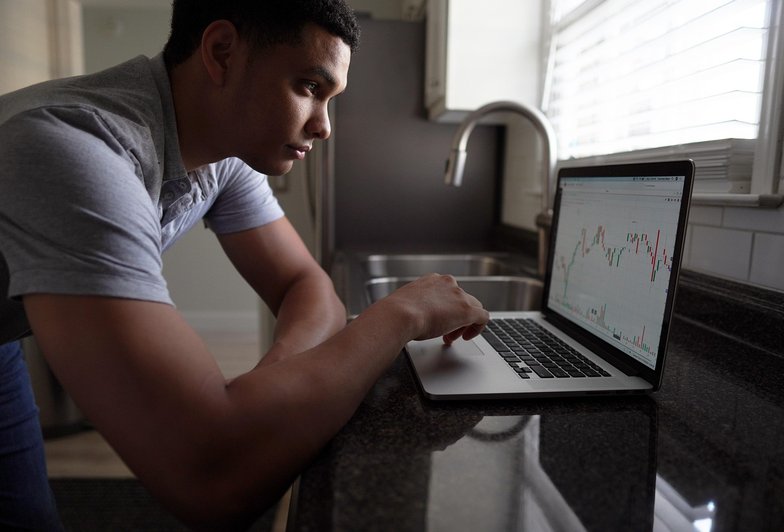
The hardest part of this strategy is not understanding it. It is resisting the urge to tinker. Financial media is designed to make you feel like you should be doing something — switching funds, timing the market, chasing whatever is hot. The evidence consistently favors the opposite: set up automatic contributions, choose low-cost broad funds, and check your balance a few times a year at most. Boring is not a bug in indexing. It is the whole point.
You do not need to pick winning stocks to build wealth — you need a boring, repeatable process and a long time horizon.
Extra income can accelerate your goals, but only if you choose a side hustle that fits your energy and schedule instead of draining both.
The standard advice says three to six months of expenses, but your right number depends on your job, your obligations, and your peace of mind.
Skip the guilt over small daily purchases and learn why your rent, car, and food choices move the needle far more than your coffee habit.
Freelancers, commission earners, and bonus-dependent workers can still build wealth with a system designed for uneven cash flow.